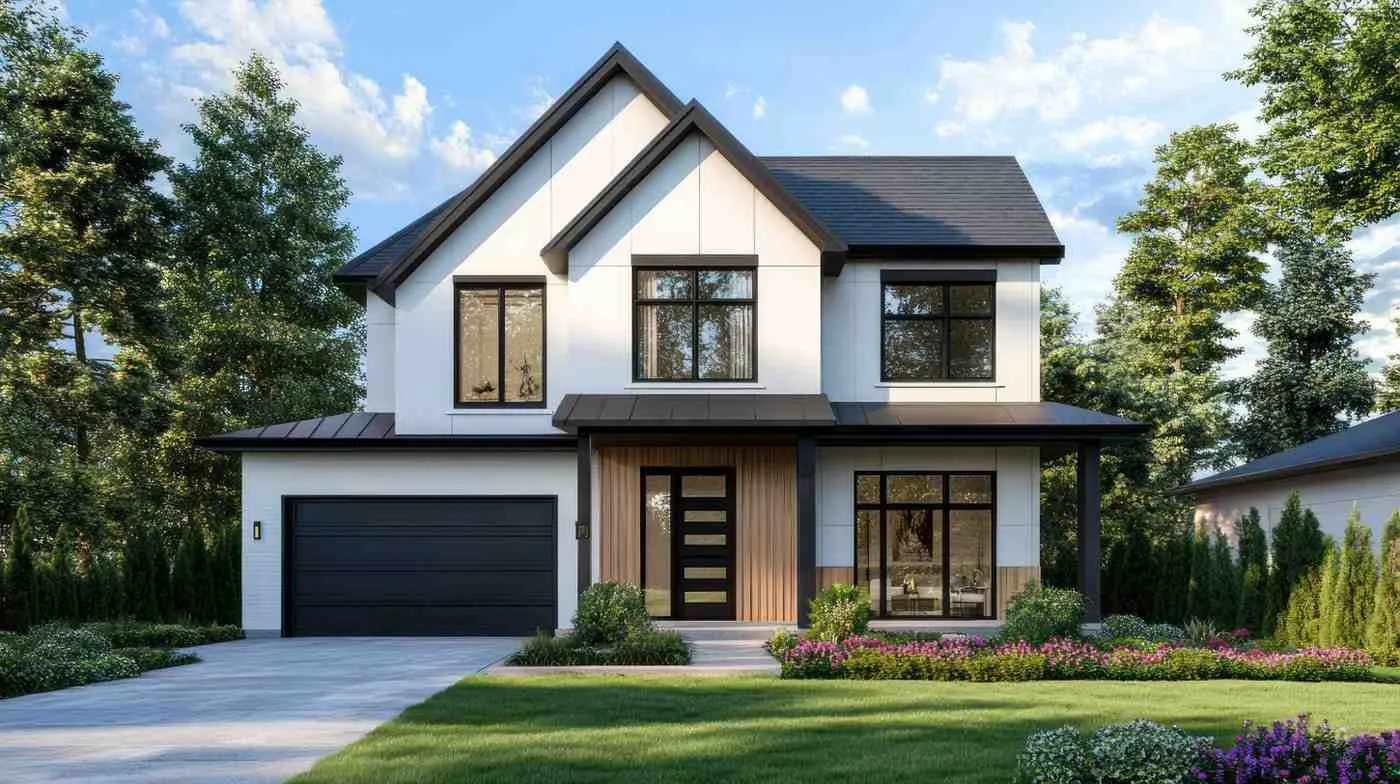
Storms roll in, pipes split and small accidents arrive with no warning at all. I build the policy around your actual house, so repair bills stay off your savings and out of your head.
I set the building limit from what a full rebuild costs today.
I write the limits and deductibles so nothing catches you out.
A policy only helps when the numbers behind it match your house. I build the limits around what your place would really cost to rebuild today.
I match the amounts to what your home really holds.
I weigh the monthly cost against the claim day cost.
I update the policy each time your house changes.
Send me the year built, roof age, square footage and a quick look at what sits inside. Five quiet minutes is all it takes.
I line up limits, deductibles and extras side by side, so the price of every choice is clear before you pick one.
Sign the option that fits your budget and cover starts the same day. I send the papers to your inbox right after.
I set it to pay for repairs or a full rebuild after fire, wind or a burst pipe, along with the things kept inside and a roof over you while the work runs.
Enough to put the same house back up at what builders charge me today. Land survives a fire, so I never copy the sale price into a policy.
A pipe that splits overnight is usually paid. Slow seepage behind a wall is not, and for water rising from outside I arrange separate flood protection.
Take photos, stop the damage spreading if it is safe, then send it to me. An adjuster agrees a repair figure and payment follows after your deductible.
Yes. Message me at renewal or sooner when something shifts, such as a new roof, a finished basement or a ring worth listing on the policy by itself.